The Home Improvement Hangover: Why Renovations Cost a Fortune
Written by Arbitrage • 2026-11-18 00:00:00
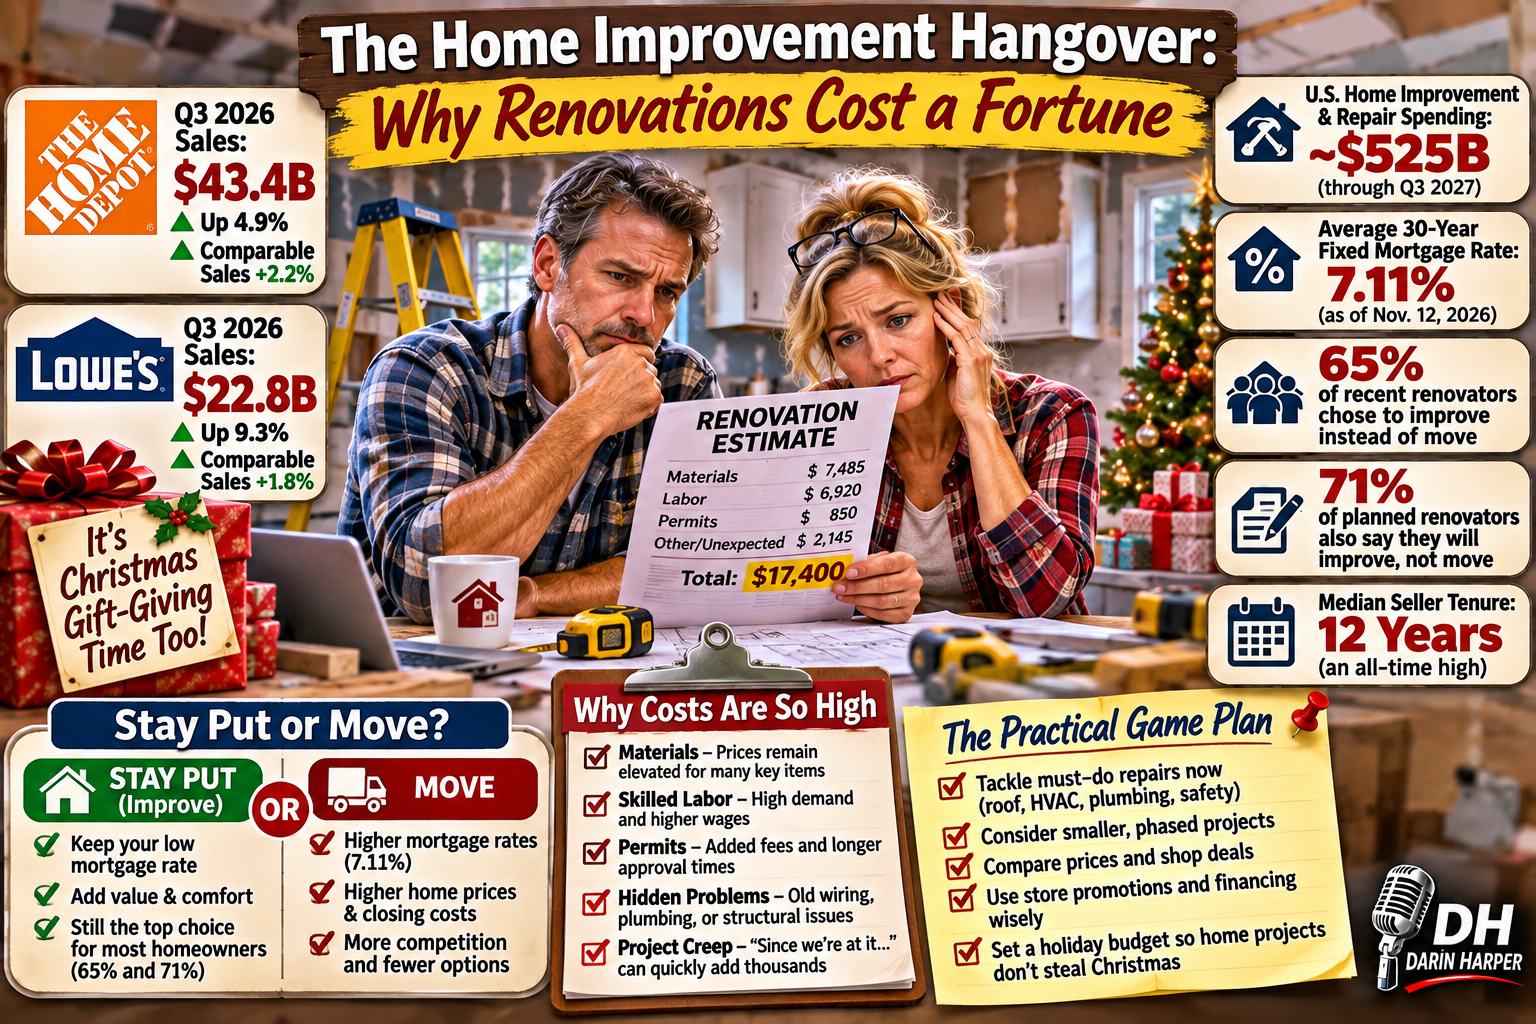
Home improvement used to sound simple: replace the kitchen cabinets, redo the bathroom, maybe knock down a wall and finally create the open floor plan everyone apparently needs before they can make spaghetti. Then the estimates arrive. Home Depot reported third-quarter sales of $43.4 billion, up 4.9% from a year earlier, with comparable sales up 2.2%. Lowe's followed today with $22.8 billion in quarterly sales, up 9.3%, and comparable sales up 1.8%, helped by strong online, professional-contractor, and home-services demand. Those numbers tell us homeowners are still spending, but they do not describe a renovation boom. They describe a country where houses keep aging, things keep breaking, and somebody eventually has to buy the lumber, faucet, furnace filter, drywall, paint, roofing materials, and mysterious $87 part that somehow holds the entire project together.
Part of the reason renovations feel so expensive is that nearly every ingredient carries a price tag. Materials are only the beginning. Skilled labor is costly, permits can add fees and delays, contractors need insurance and overhead, and older homes have a special talent for revealing three additional problems the moment one wall comes down. Labor alone explains part of the sticker shock: average hourly earnings across construction reached $42.03 in October, while residential remodelers averaged about $38.37 an hour. Then comes the phenomenon known to every homeowner as "while we're at it." If you are already replacing the floor, maybe you should paint the room. If you are painting the room, maybe the lighting should be updated. Congratulations: the $4,000 project has discovered compound interest.
Yet homeowners are not exactly abandoning renovation. Harvard's Joint Center for Housing Studies expects annual spending on home improvements and repairs to hover around $525 billion through the third quarter of 2027, even though growth is projected to remain sluggish. That makes sense because many projects are not glamorous upgrades; they are repairs that can only be postponed for so long. The roof does not care that Christmas is six weeks away. The water heater is unmoved by your gift budget. The HVAC system has never once checked whether you have already bought presents for the grandchildren. Cash still funds most remodeling: Harvard found that 63.8% of homeowner improvement spending was primarily paid with cash in its latest detailed financing analysis. That means home repairs often compete directly with savings, travel, holiday spending, and every other household priority.
That competition becomes especially uncomfortable right now. November and December already ask households to pay for Thanksgiving meals, Christmas gifts, travel, decorations, parties, and year-end expenses. A new roof arriving on the same budget spreadsheet as a new bicycle for a child is not festive financial planning. So homeowners prioritize. A leaking pipe gets fixed; the dream bathroom waits. A failing refrigerator gets replaced; the decorative backsplash can survive another year. This helps explain why home-improvement retailers can still produce billions in sales while the broader remodeling market feels subdued. People are buying what their homes require, but many are postponing the large discretionary projects that once started with the phrase, "Wouldn't it be nice if..."
Moving is not necessarily the escape hatch. Freddie Mac's latest weekly survey puts the average 30-year fixed mortgage rate at 7.11%. Meanwhile, Redfin found earlier this year that roughly 65% of homeowners who had recently renovated chose to improve their existing home instead of moving, while 71% of people planning renovations said the same thing. About 80% of homeowners with mortgages had rates below prevailing market levels, giving millions of households a powerful reason to protect their old mortgage rather than trade it for a much more expensive new one. The National Association of Realtors says sellers are now staying in their homes a median of 12 years, an all-time high, with the mortgage lock-in effect contributing to that longer tenure. When the choice is a $35,000 kitchen remodel or buying another house at today's prices and borrowing costs, suddenly those cabinets begin to look almost reasonable.
The home-improvement hangover, then, is really the collision of three realities: houses need maintenance, renovations remain expensive, and moving is not especially cheap either. The best defense is less exciting than a television makeover reveal. Separate repairs from wants, get multiple estimates, build a contingency fund into every project, avoid financing cosmetic upgrades at high interest rates when possible, and decide which improvements actually improve your life rather than simply improving the photographs. Better days for remodeling would likely require some combination of lower mortgage rates, lower financing costs, steadier material prices, and stronger household budgets. Until then, millions of homeowners will keep doing what they have been doing: staying put, fixing what absolutely needs fixing, postponing what can wait, and hoping the dishwasher understands that Christmas is already expensive enough.